Rahul, a 29-year-old engineer in Bengaluru, started investing in 2021. He bought whatever his office WhatsApp group was excited about. Some stocks doubled. Others halved. Five years on, he owns 23 stocks and four mutual funds, and has no idea if he’s on track for anything.
Sound familiar? More Indians are investing than ever before. Monthly SIP contributions hit a record ₹32,490 crore in September 2026. But putting money in is the easy part. Knowing why you own what you own, and sticking with it through bad years, is much harder.
That’s where a good stock investment advisor comes in. Not to hand out hot tips, but to help you build a plan you can actually live with. Here’s how stock market advisory services work for long-term investors, and what a stock investment advisor can and can’t do for you.
The Short Answer
A stock investment advisor helps you build a long-term strategy by first understanding your goals, timeline and comfort with risk. They then suggest an asset mix, pick a diversified set of stocks or funds, and review it regularly. Just as important, they keep you steady during market falls, when panic decisions tend to cost investors the most.
Context and Background
Ten years ago, investing in shares felt like something only “market people” did. Today, opening a demat account takes ten minutes on your phone. India now has around 10 crore active SIP accounts, and SIP assets stood at about ₹17.86 lakh crore in September 2026.
With that growth came a flood of advice. YouTube, Telegram and Instagram are full of people telling you what to buy. But not all advice is the same.
In India, SEBI-registered investment advisers (RIAs) give personalised advice for a fee. Research analysts publish stock views and recommendations. And then there are tipsters, who often aren’t registered at all. For a long-term plan, you want someone who looks at your whole financial life, not just tomorrow’s hot stock. You can check any adviser on SEBI’s list of registered investment advisers.
Key Insights: How an Adviser Actually Builds Your Plan
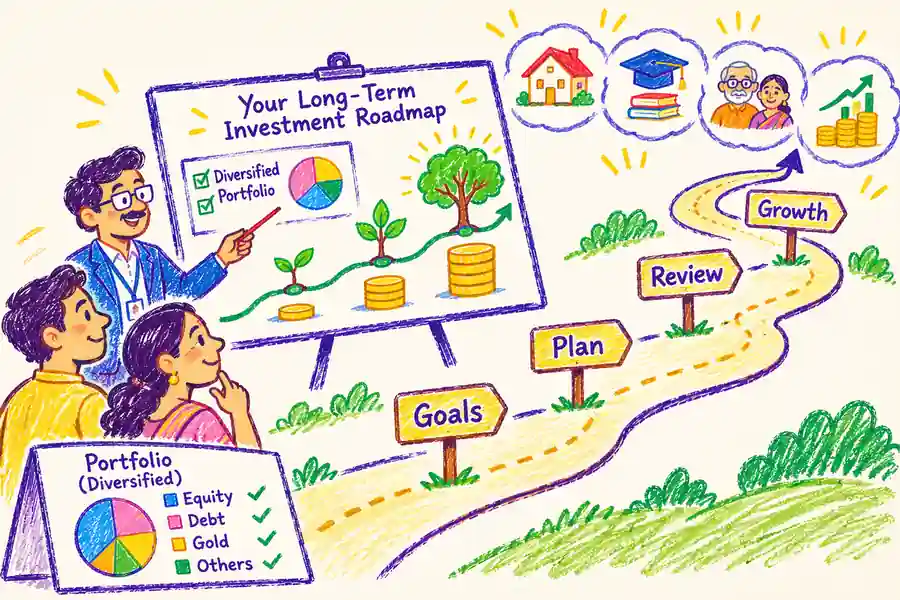
A good adviser doesn’t start with stock names. They start with you. Here’s roughly how the process works.
- Your goals come first. Say Rahul wants ₹50 lakh for his daughter’s education in 15 years, plus a retirement fund. Each goal gets its own timeline and target, so every rupee has a job.
- Then the asset mix. Money needed in two years shouldn’t sit in volatile small-cap stocks. Money for 20 years from now can take more risk. The adviser splits your savings across equity, debt and perhaps gold based on this.
- Then the actual picks. Instead of 23 random stocks, you might end up with a focused set of quality companies and a few low-cost funds, spread across sectors.
- Regular check-ups. Once or twice a year, the adviser reviews the portfolio and rebalances if one part has grown too big.
The quieter part of the job is behaviour. In SEBI’s latest study of F&O traders, 87.7% of individual traders lost money in FY26. Even SIP investors get nervous: in October 2025, SIP closures equalled about 75% of new SIPs opened that month. An adviser’s calm voice during a falling market can be worth more than any single stock idea.
Impact and Implications
For investors, the biggest change is clarity. You stop asking “what should I buy today?” and start asking “am I on track?” That shift alone tends to reduce random buying and selling.
For businesses, patient investors matter too. Companies benefit when more of their shareholders hold for years rather than weeks. And advisory firms that focus on planning, not tips, are slowly building trust with a new generation of clients.
For everyday families, it means saving with a purpose. A home down payment, a child’s college fees, a comfortable retirement: each gets a plan instead of a hope.
Opportunities and Risks
The upside is fairly clear. You get a structured plan, someone to check your blind spots, and a second opinion before big decisions. Over 10 or 15 years, avoiding a few costly mistakes can make a real difference.
But there are limits. No adviser can predict the market or promise returns, and anyone who does is a red flag. Advice also costs money. For individuals, SEBI caps adviser fees at ₹1.51 lakh per family a year, or 2.5% of the assets being advised on. Make sure the value you get justifies what you pay.
Quality varies, too. Ask how they pick investments, how often they’ll review your plan, and how they’re paid. If the answers feel vague, keep looking.
Future Outlook
The trends point one way. SIP contributions have set new records through 2026, and more first-time investors are entering every month. Many of them will need help turning scattered investments into a real plan.
At the same time, SEBI keeps tightening the rules on fees, disclosures and who can give advice. Expect more hybrid models too, where digital tools handle tracking and a human adviser handles the bigger conversations. The tools will change. The basics of goals, diversification and patience probably won’t.
Conclusion
A long-term strategy isn’t about finding the next multibagger. It’s about knowing your goals, owning the right mix, reviewing it calmly, and not panicking when markets fall. A good adviser helps with all four.
Remember Rahul? With a clear plan, his 23 random stocks could become a portfolio with a purpose. Yours can too. The earlier you start, the more time does the heavy lifting for you.