When several people share one health insurance policy, their healthcare needs will not always be the same. Your child may need treatment for an injury, while a parent may need care for an ongoing condition. Yet, under a family floater, they may all draw from the same sum insured. That is why it is important to understand how the shared cover works and which terms can limit it.
How Does a Family Floater Policy Work?
A family floater gives the insured family members access to one shared sum insured during the policy period. The available amount can be used by one member or several members, depending on their covered medical needs and the policy terms.
Consider an example:
If your family has a ₹10 lakh floater sum insured and one member uses ₹4 lakh for an eligible claim, the balance amount for the rest of the family is ₹6 lakh, subject to the applicable policy terms.
| Feature | Individual Policy | Family Floater |
| Sum insured | Allocated to one insured person | Shared among covered members |
| Use of cover | Used by the individual | Can be used by one or more members |
| Policy arrangement | Separate cover for each person | One shared cover for the listed family members |
That shared pool is the key difference to keep in mind when you assess family health insurance plans.
What Expenses May a Family Health Insurance Policy Cover?
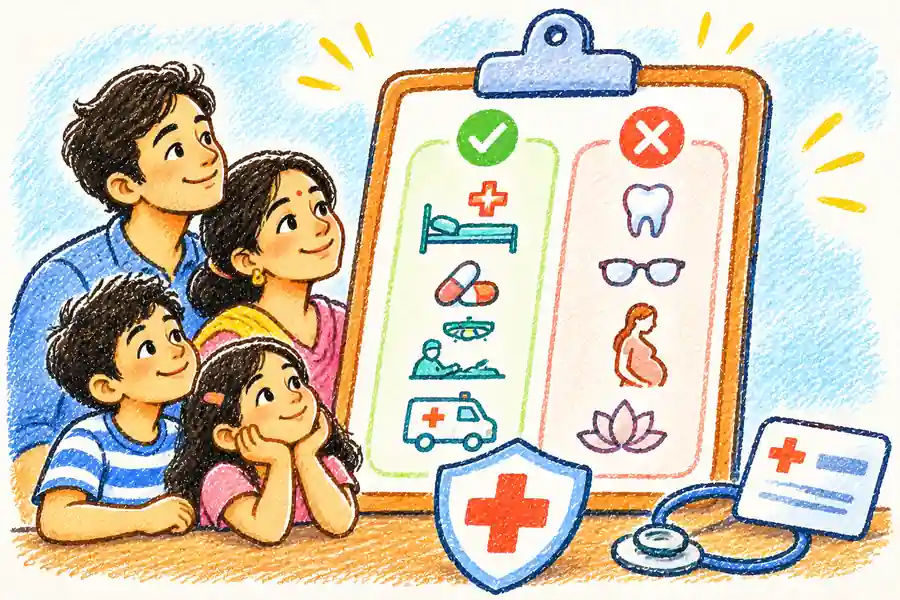
Depending on the terms, a health insurance policy may provide cover for eligible hospitalisation expenses and certain related costs.
These may include:
- In-patient treatment: Eligible medical expenses during a covered hospital stay.
- Day-care procedures: Specified procedures that do not require a 24-hour hospital stay.
- Pre-hospitalisation expenses: Certain eligible medical expenses incurred before hospital admission.
- Post-hospitalisation expenses: Specified expenses incurred after discharge.
The period, limits, and conditions attached to these benefits can differ between policies. Check the policy wording for the exact coverage.
What May Fall Outside the Policy’s Coverage?
Certain treatments, expenses, or situations may be excluded, while others may be subject to waiting periods, sub-limits, or co-payment.
For example, you may come across:
- Waiting periods: Some conditions or treatments may be subject to a specified waiting period.
- Pre-existing disease conditions: A policy may apply a waiting period or other terms to pre-existing diseases.
- Sub-limits: Particular treatments or expenses may have a separate monetary limit.
- Exclusions: Certain expenses or treatments may not be covered under the policy.
- Co-payment: You may have to bear a specified portion of an admissible claim when this condition applies.
What Should You Check Before Choosing Family Health Insurance?
Before choosing a policy, look at how the shared cover fits the people you want to insure.
Pay particular attention to:
- The total sum insured
- Who can be covered under the policy
- Waiting periods and pre-existing disease conditions
- Sub-limits and co-payment
- Exclusions and other restrictions
- Renewal terms and continuity conditions
A family floater can be convenient when several people share one policy, but its shared sum insured also means that one member’s covered expenses can reduce the amount available to others during the same policy period.
Conclusion
Family health insurance is not just about putting everyone under one policy. The important detail is how that shared cover works when different family members need medical care at different times. Once you understand the common sum insured and the conditions attached to it, you can assess the policy on what it actually offers rather than assuming that every medical expense will be covered.