When it comes to building long-term wealth, most people eventually come across two popular investment options – Unit Linked Insurance Plans (ULIPs) and Systematic Investment Plans (SIPs). While they’re often compared against each other, they are designed to solve different financial needs. One combines market-linked investing with life insurance, while the other helps you invest systematically in mutual funds.
Instead of asking which one is better, a smarter question is whether you can use both to create a stronger financial portfolio. The answer, for many investors, is yes. When used strategically, a ULIP and an SIP can help you grow wealth, manage financial risks, and stay disciplined throughout your investment journey.
Why Are ULIPs and SIPs Often Compared?
Both ULIPs and SIPs invest your money in market-linked instruments, making them popular choices for long-term wealth creation. However, their structure and objectives differ significantly.
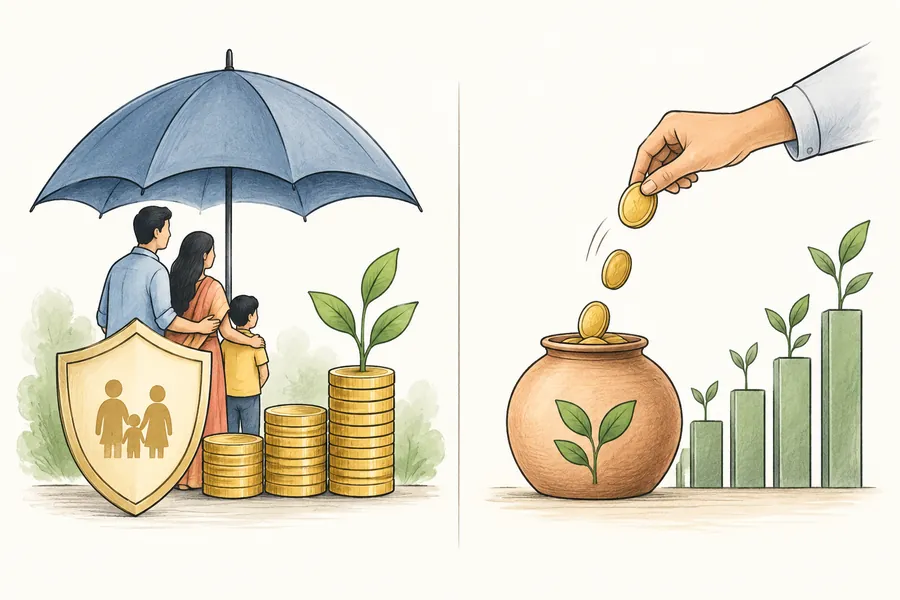
A ULIP combines investment with life insurance, whereas an SIP is simply a method of investing regularly in mutual funds.
| ULIP | SIP |
| Investment + life insurance | Investment in mutual funds |
| Offers financial protection | Pure investment vehicle |
| Long-term commitment | Flexible investment option |
| Suitable for goal-based planning | Suitable for wealth creation through disciplined investing |
Understanding these differences helps you decide how each product fits into your financial plan.
Should You Choose a ULIP or an SIP?
Many investors assume they must choose one over the other. In reality, they serve different purposes.
A ULIP is suitable if you want life insurance and market-linked investments under a single product. An SIP, on the other hand, is ideal if your primary objective is building wealth through regular mutual fund investments.
Rather than replacing one another, they can work together to help you achieve multiple financial goals.
What Makes a ULIP Scheme Different From an SIP?
A ULIP scheme allocates a portion of your premium towards life insurance while investing the remaining amount in equity, debt, or balanced funds, depending on your risk appetite.
Some key features include:
- Life insurance cover throughout the policy term.
- Flexibility to switch between available fund options.
- Long-term wealth creation potential.
- Goal-based investing for retirement, children’s education, or other milestones.
Since a ULIP scheme combines protection and investment, it appeals to investors looking for an all-in-one financial solution.
How Does an SIP Help You Build Wealth?
An SIP encourages disciplined investing by allowing you to invest a fixed amount at regular intervals in mutual funds.
Instead of trying to time the market, you invest consistently regardless of market conditions. Over the long term, this approach benefits from rupee cost averaging and the power of compounding.
Whether you’re investing for retirement, buying a home, or building long-term wealth, an SIP helps you stay invested without requiring a large lump sum.
How Can a SIP Calculator Improve Your Financial Planning?
Before starting an SIP, it’s useful to estimate how your investments could grow over time.
A SIP calculator helps you project your investment value based on:
- Monthly investment amount
- Expected annual return
- Investment duration
For example, if you invest ₹10,000 every month for 20 years, a SIP calculator provides an estimate of your potential corpus based on assumed returns. This helps you determine whether your current investments are sufficient to achieve your financial goals.
Reviewing these projections regularly also allows you to increase your investments as your income grows.
Can You Include Both in Your Investment Plan?
Absolutely.
An effective investment plan does not rely on a single financial product. Instead, it combines products that address different financial needs.
For example:
- Use a ULIP for long-term goals that require both insurance and investments.
- Invest through SIPs to build additional wealth and diversify your portfolio.
This approach gives you the benefits of life insurance while allowing your mutual fund investments to grow independently.
A diversified investment plan also reduces the risk of depending entirely on one investment product.
What Are the Biggest Advantages of Combining ULIPs and SIPs?
Using both products together offers several benefits:
- Diversification across different financial products.
- Long-term wealth creation through market-linked investments.
- Financial protection through life insurance.
- Disciplined investing habits.
- Flexibility to pursue multiple financial goals simultaneously.
By allocating your savings across both, you create a more balanced portfolio that addresses both wealth creation and financial security.
What Mistakes Should You Avoid While Investing?
Regardless of whether you choose a ULIP or SIP, avoid these common mistakes:
- Investing without clearly defined financial goals.
- Stopping investments during market volatility.
- Ignoring the importance of adequate life insurance.
- Focusing only on short-term returns.
- Not reviewing your portfolio periodically.
Consistent investing and regular portfolio reviews often have a greater impact on long-term wealth than trying to predict market movements.
How Can You Build a Smarter Long-Term Investment Plan?
A practical strategy is to use both products according to their strengths.
You can:
- Identify your long-term financial goals.
- Select a suitable ULIP scheme if you require life insurance with investments.
- Start SIPs for additional wealth creation.
- Use a SIP calculator every year to track your projected corpus.
- Increase your investments as your income grows.
- Review your portfolio regularly and rebalance it whenever necessary.
This balanced investment plan allows you to pursue multiple financial goals without relying entirely on a single investment avenue.
Conclusion
Financial planning becomes more effective when each product serves a specific purpose instead of trying to do everything on its own. A ULIP scheme can help you combine insurance with long-term investing, while SIPs allow you to build additional wealth through disciplined mutual fund investments. Rather than debating which option is superior, focus on how each fits into your broader investment plan. By staying invested consistently, reviewing your progress with a SIP calculator, and aligning your investments with your financial goals, you can build a portfolio that supports both wealth creation and long-term financial security.